

Bid Auto
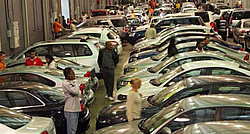
New initiativesInvestment in dealership infrastructure was maintained in accordance with our contractual obligation to brand principals. Investment totalled R180 million. Investment was also made to pursue improved efficiency and in support of operations with good profit potential. For instance, our Fleet Active IT system was implemented at McCarthy Fleet Solutions. A materials handling division was added to our heavy equipment business and we are pursuing the acquisition of the distribution rights to the Nissan and Fantuzzi forklift ranges. Sales teams innovated constantly. Our mega-promotions – “The Sale of All Sales” – turned Nasrec and the Durban Exhibition Centre into sales lots with more than 1 000 vehicles on display at each venue. Losses within our vehicle import and distribution business prompted a review of costs, risks and structures. A joint venture has been formed with the Imperial Group. Collaboration with a competitor is unusual, but the challenges facing our industry are unprecedented and collaborative efforts that reduce costs have to be explored. Risks to the businessThe severity of the world financial crisis and major contraction within the automotive industry have emphasised risk in our sector as never before. In the past, “principal risk” generally referred to the danger of losing a brand that was reallocated to a competitor. In today’s environment, it is apparent that no business is too big to fail. A principal is therefore at risk, even a large international brand. Bankruptcy of a major manufacturer would obviously bring an end to local operations on behalf of that brand. Alternatively, radical rationalisation by a deeply indebted company could result in rapid withdrawal from our market. Considerable investment is undertaken at the behest of manufacturers. Such investment is justified by key assumptions, including the assumption that the principal will stay in business. In recent times, investment in dealership infrastructure at McCarthy has averaged R250 million a year; most of which is undertaken to support manufacturer demands for quality facilities. High losses by major manufacturers have prompted a search for new partners. International realignment can result in mis-alignment at dealership level. “Sister brands” can suddenly be separated, leaving a dealer with unused showroom space because volumes have halved in the wake of the separation. These risks always existed. They have been magnified by the financial crisis. Sensitivity to economic climate change has always been a risk. Car sales are habitually used by economists as a key indicator of economic health or distress. Again, this risk has been underlined. Credit conditions also create risk. The danger of bad debt is well understood and can be addressed internally through normal credit processes. However, international markets have witnessed the sudden severing of credit lines to previously stable companies. Drastic action like this can turn a previously safe corporate customer into a risky proposition. “Normal” credit processes may not pick up an “abnormal” risk such as this. Such developments reinforce the need for caution when advancing credit. In a downturn crime risk tends to increase and all anti-theft and anti-fraud procedures were reviewed. New risk management systems have been introduced. Organisational cultureTeam spirit came to the fore in the industry crisis. Morale proved resilient as a result of good two-way corporate communication and general appreciation for efforts to avoid major retrenchments. Working over weekends and holidays showed the level of commitment and the benefit of our participative management style.
Despite recent challenges, Bid Auto has remained cash generative while our fleet, parts, servicing and used-vehicle operations have scored significant successes. In contrast, many industry peers face increasing pressure. Casualties appear inevitable. A smaller retail industry footprint will create opportunities to increase throughput. We remain confident of our ability to benefit from rationalisation and improve our market position. We expect to achieve meaningful trading profit growth in the coming year. Bid Auto will be restructured into a more focused and decentralised automotive business with its ancillary services, a leasing and financing arm and an import and distribution business. These changes will cater for succession as well as position the constituent segments for further expansion. Acquisition opportunities will be aggressively pursued. In the longer term, there is broad consensus the global automotive industry is in the process of fundamental change. The need for convenient personal transport will not go away; some weaker brands may fall by the wayside. Bid Auto’s core brand – McCarthy – has been in business 99 years and has managed numerous changes. We are confident we will successfully manage the next wave of change and achieve sustained growth as we enter our second century.
|
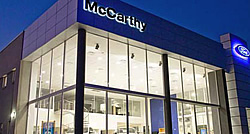
PeugeotRestructure and rationalisation resulted in our relocation from Rivonia to Woodmead, Johannesburg, and the integration of our Pietermaritzburg dealership with the Value Centre. The model line-up was recently enhanced. ToyotaNew dealerships were opened at Gezina, Hatfield and Lynnwood while a Lexus Lynnwood dealership was launched. Our profit contribution deteriorated significantly, though aftersales operations continued to perform well. An accessory products internet site to support our McCessories programme has been launched. Our used-vehicle sales are positioned to benefit from the wider spread of Toyota models in Budget Rent a Car’s fleet. |
  |
Volkswagen/Audi/VW Commercial
The VW/Audi franchise performed ahead of budget, with a strong contribution from aftersales. Audi introduced several new models and all Audi dealership upgrades were completed. The Audi Centre in Umhlanga now operates from a standalone site.
Volkswagen of South Africa has ceased new vehicle sales of SEAT. We continue to provide aftersales support.
MAN Truck & Bus Africa and Volkswagen SA have integrated their local truck and bus operations. Our VW Commercial dealership in Witbank will offer sales and aftersales support.
Value Centres
In an effort to stem the substantial losses, seven outlets were closed. Where possible we have also incorporated standalone Value Serve operations into the Value Centres, creating 11 national operations. We retained four standalone Call-a-Car Direct dealerships.
The Suzuki franchise performed above expectations. A sixth dealership opened in Bloemfontein in July.
Burchmores
Burchmores performed well, achieving significant profit growth. Collaboration with McCarthy dealerships facilitated selling success. Surplus McCarthy stock is now retailed by us rather than disposed of to the trade. Our “wholesale to the public” positioning has helped us become the pre-eminent destination for value-conscious used-vehicle buyers.

Bidvest's vision lies in the realm of possibility
“Bidvest people put in a resilient performance and the Group achieved a creditable result.”
statement
“We refuse to participate in the recession and salute our employees for their efforts in exceptionally difficult trading conditions.”